If your finance team emails a PDF tax invoice and considers the job done, this article is for you. Under the UAE's mandatory e-invoicing system, that PDF is not an eInvoice ââ¬â and from 2027, issuing it will not satisfy your invoicing obligations for in-scope transactions.
The Ministry of Finance (MoF) is explicit: an eInvoice is structured invoice data that is issued and exchanged electronically between supplier and buyer and reported electronically to the Federal Tax Authority (FTA). Unstructured formats ââ¬â PDF, Word, images, scans, even invoices attached to email ââ¬â do not count.
Below is a plain-English guide to what the 2026 rules actually require, who they cover, and the dates that matter.
1. What an eInvoice is ââ¬â and what it is not
| Is an eInvoice | Is NOT an eInvoice |
|---|---|
| Structured XML data in the UAE's PINT-AE format | A PDF tax invoice emailed to a customer |
| Issued and exchanged through an MoF-Accredited Service Provider (ASP) | A Word document or scanned paper invoice |
| Tax data reported electronically to the FTA | An image, photo, or email attachment |
| Machine-readable, validated, and traceable | A spreadsheet export |
The eInvoice itself also does not carry a QR code or barcode ââ¬â a common point of confusion. Your existing VAT tax-invoice content obligations continue; the eInvoice is the structured data layer, not a replacement for a readable commercial invoice.
2. How the UAE model works (in plain language)
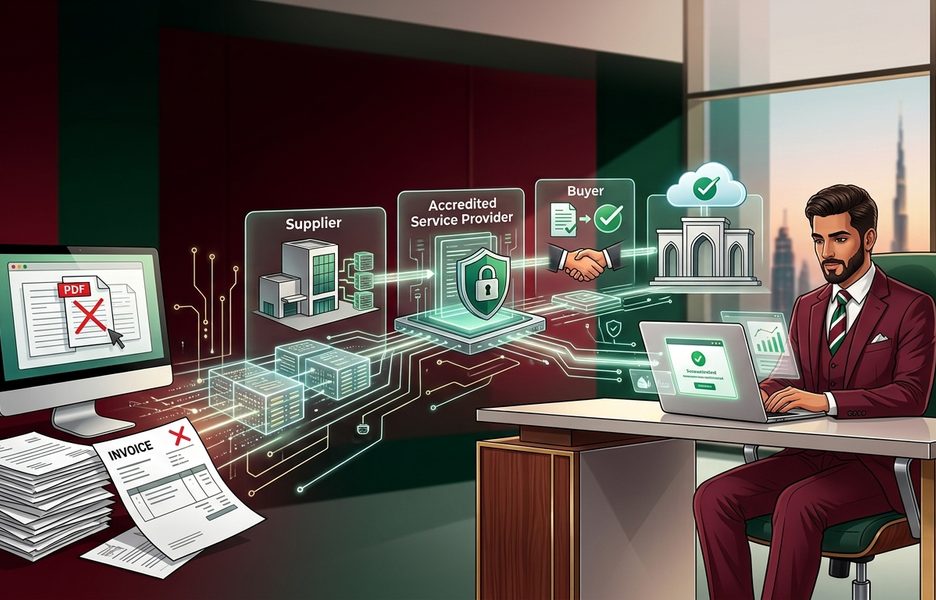
The UAE uses a "five-corner" DCTCE (Decentralised Continuous Transaction Control and Exchange) model built on the OpenPeppol network:
- Corner 1 ââ¬â Supplier: issues invoice data from its business software.
- Corner 2 ââ¬â Supplier's ASP: validates the data against the PINT-AE standard, converts it to the UAE XML format, and transmits it over the Peppol network. In parallel, it reports the Tax Data Document (TDD) to the FTA.
- Corner 3 ââ¬â Buyer's ASP: validates and delivers the data.
- Corner 4 ââ¬â Buyer: receives the structured data into its own software.
- Corner 5 ââ¬â MoF/FTA Central Data Platform: receives the tax data for storage and analysis.
Every business appoints one ASP for both sending and receiving. Your participant identifier is based on 0235 + your 10-digit TIN, and your TIN is the first 10 digits of your TRN.
3. Scope decision tree: does this apply to your business?
Work through these questions in order:
Q1. Do you conduct business transactions in the UAE? The scope is broad: it generally covers persons conducting business transactions in the UAE regardless of VAT registration status. Non-VAT-registered businesses are not automatically outside the system.
Q2. Who is your customer? - B2B, B2G, G2B, and G2G flows: in scope. - B2C (consumer) transactions: generally outside the system for now. But if you sell to both consumers and businesses, your B2B invoices are still in scope ââ¬â consumer sales are not a blanket exemption for the company.
Q3. Are you in an excluded category? Only narrow exclusions exist (covered in Part 2 of this series): certain sovereign government activities, specified airline transactions, and qualifying exempt financial services. Free-zone status and non-VAT registration are not exclusions.
Q4. Which phase are you in? See the timeline below ââ¬â the phase depends on revenue (and entity type), not on your VAT registration.
4. What the mandate does NOT replace
- VAT tax-invoice obligations remain. Your invoices must still meet Federal Decree-Law No. 8 of 2017 content requirements.
- Credit notes and accounting controls remain. You still need proper books, reconciliation, and 7-year record retention.
- A readable invoice may still be needed. During transition, a buyer may ask for a human-readable version alongside the structured eInvoice.
5. The timeline ââ¬â ASP appointment vs go-live (two different milestones)
| Phase | Who | Revenue | ASP appointment deadline | Mandatory go-live |
|---|---|---|---|---|
| Pilot / Voluntary | Selected working group / any business | Any | From 1 Jul 2026 | From 1 Jul 2026 (voluntary) |
| Phase 1 | Large businesses | ââ°Â¥ AED 50m | 30 Oct 2026 (extended from 31 Jul 2026) | 1 Jan 2027 |
| Phase 2 | SMEs | < AED 50m | 31 Mar 2027 | 1 Jul 2027 |
| Government | Government entities | ââ¬â | 31 Mar 2027 | 1 Oct 2027 |
Important: the MoF extended the Phase 1 ASP appointment deadline from 31 July 2026 to 30 October 2026 (10 May 2026 amendment to Ministerial Decision No. 244 of 2025). The go-live date did not move. If you are Phase 1, the practical runway between appointing an ASP and going live is now only about nine weeks ââ¬â the extension shortened your implementation window, it did not relax it. Always re-check the live MoF portal before relying on any date.
6. Common owner blind spots
- "We email PDFs, so we're already e-invoicing." No ââ¬â see Section 1.
- "We're not VAT registered, so it doesn't apply." Scope follows business transactions, not VAT registration.
- "We're in a free zone, so we're exempt." Free-zone status alone is not an exclusion (see Part 2).
- "We only sell to consumers." If any of your sales are B2B, those invoices are in scope.
- "We have several entities ââ¬â one registration will do." Each legal person has its own TIN, participant identifier, and ASP onboarding.
- "The PDF is our source record." Under the new system the structured XML is the authoritative invoice data; your record-keeping must handle both.
7. Check your business ââ¬â mini checklist
- We conduct business transactions in the UAE (B2B and/or B2G)
- We know each legal entity's revenue band vs the AED 50m threshold
- We know our TRN/TIN and can derive our participant identifier (0235 + TIN)
- We understand ASP appointment and go-live are separate deadlines
- We have identified which invoices are B2B vs B2C
- We know our ASP appointment deadline
- We have a plan for readable invoices during transition
Frequently Asked Questions
Is e-invoicing mandatory in the UAE? Yes, in phases. Voluntary exchange began 1 July 2026; mandatory e-invoicing applies to large businesses (revenue ââ°Â¥ AED 50m) from 1 January 2027, smaller businesses from 1 July 2027, and government entities from 1 October 2027.
Is a UAE e-invoice the same as a PDF tax invoice? No. A PDF is a static document and is explicitly not an eInvoice under the MoF framework. An eInvoice is structured XML data (PINT-AE) exchanged through an accredited service provider with tax data reported to the FTA.
Do non-VAT-registered businesses need to comply? Generally, yes if you conduct in-scope business transactions in the UAE. The scope test is not the same as the VAT registration threshold. Confirm your specific position against the current MoF guidelines.
Does the eInvoice replace my VAT tax invoice? No. Tax-invoice content obligations under VAT law continue. The eInvoice adds a structured, machine-readable data layer; a readable commercial/tax invoice may still be needed during transition.
What happens if I miss the ASP appointment deadline? From your go-live date, an invoice that doesn't meet e-invoicing requirements risks not being treated as a valid tax invoice ââ¬â affecting your customers' input VAT recovery and exposing you to penalties under Cabinet Decision No. 106 of 2025.
Can I issue e-invoices voluntarily before my mandatory phase? Yes ââ¬â voluntary exchange and reporting over the Peppol network has been open to all UAE businesses since 1 July 2026.
Next in this series: Now that you know whether the system may apply, read Part 2 ââ¬â UAE e-invoicing edge cases for VAT groups, free zones, non-VAT businesses and exclusions.
Sources: UAE Ministry of Finance eInvoicing portal (mof.gov.ae, checked 10 Oct 2026); UAE Electronic Invoicing Guidelines v1.1 (1 Jun 2026); Ministerial Decision No. 244 of 2025 and Ministerial Resolution No. 66 of 2026; Cabinet Decision No. 106 of 2025.
Disclaimer: This article is general information, not legal or tax advice. Verify current requirements with the MoF portal or a qualified UAE tax adviser before acting.